share

Precious Metal Quotes from KITCO

Showing posts with label gold mining. Show all posts

Tuesday, 18 October 2011

Graphite and Gold = Perfect Hedge?
Graphite and Gold = Perfect Hedge?
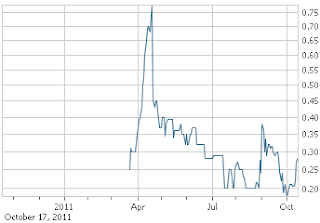
Share Price: 28 cents

Shares O/S: 30 Million 

Market Cap: 8.4 Million

Rating: Strong Buy 

Ticker Symbol: SRK 

On this week’s edition of Resource Corp I will be featuring a hot new company that has their hands in pretty much every basket. Strike Gold, a major player in the graphite industry, has recently acquired a game changing project from Canaco Resources.

 Canaco + Strike Gold 

In addition to the current Satterly Lake property in Ontario, Strike Gold announced yesterday that they will be entering into a joint venture with Canaco Resources. For those of you unfamiliar with Canaco, they are a key player in Tanzania. An updated resource estimate for Canaco is currently in the works, but based on my analysis, it can be estimated easily to the tune of 5 million ounces.

In addition, the Boma property in Tanzania is accessible by paved highway; always an unexpected delight to those familiar with African exploration.

The Boma property has never been drilled or mapped with modern geological technology which means this property has blue sky potential.  Multi-million ounce deposits are the norm in the surrounding region, making this property the quintessential property of elephant territory.

The geological landscape of Boma is very similar to the Handeni property, Canaco’s flagship project.  Based on preliminary assessments, Boma is expected to hold yields similar to those of Handeni  Property.

Property Overview Map

The Boma property is also along the same corridor that currently hosts two active gold mines. Scaling in at nearly 562 square kilometers, the Boma property is massive.  This property truly has the potential to be multi-million ounce project.  Naturally, with Canaco on board, Strike Gold will have no issues dealing with the authorities in Tanzania, which is always attractive to investors.

I will be following this project very closely as more geological work, specifically airborne surveys and on-the-ground sampling becomes available. I will be updating the blog regularly. I truly believe that this property has the potential to be a multi-million ounce deposit.

  Project highlights:
  • Connected by Highway
  • Joint Venture with Canaco
  • Elephant Territory
  • Large Land Base

Ontario... New Gold Rush?

In addition to this new property, Strike Gold has also made advancements in Ontario, which includes the Satterly Lake Project. There has been much historic drilling on this property which is not yet NI 43101 compliant.

Highlight drill hole to date:
  • 1.37gpt over 117m 


There has also been very positive grab samples, Ontario is having a renissance simlar to the gold rush with companies like Augen Gold, Trelawney, and Gold Canyon which I recently featured in an ariticle a few months ago. The property hosts sulfides that are all usually gold bearing;the geological landscape of this project looks similar to springpole lake. The Bircho-Urchi greenstone belts are similar to Red Lake, where Goldcorp has a flagship-mining prokect. The red lake mining project has one of the lowest cash costs coming in at 288 dollars a oz. 

The Next Critical Metal?

Strike Gold also hosts two great high grade graphite deposits, for those of you guys thinking WTF is graphite? I have a paragraph below explaining the importance of this metal.
Graphite 101

A key reason that I like Strike Gold is in addition to the gold is because the company has 2 world class graphite exploration plays. The demand for graphite is rising at astronomical rates. The need for lightweight and high strength Carbon fibre is creasing as the world moves to more fuel efficient cars/jets for example the new Boeing dream liner is made almost entirely out of carbon fibre. This is supposed to be the replacement for the aging 747. Graphite is also used in nuclear reactors, fuel cells, batteries, solar cells, and most importantly in hockey sticks used by the NHL greats!

With great demand like this, I can see China curbing their exports.  This is an highly expected move by China because they also curbed their exports of Rare Earth Metals in the past year. North America is becoming considerably more aware of factors such as these so I believe they will be working hard to secure critical supply of these niche metals.
Recently Graphite prices have hit $3000 dollars/ton.  Although they have pulled back recently with this bear market, they have made great moves that can only be matched by the tremendous rise in gold prices. Graphite is clearly in a bull market rally I believe this trend will continue as we become more sophisticated and more aware of the environment.
I will not get into detail about the Graphite deposits at this time but here are the highlights for more information on them check out the Powerpoint Presentation 

Now is a great time to buy Strike Gold as there will be a sister company known as Strike Graphite, with a market cap like this it is clear the Graphite assets are being valued at ZERO, so a spin out will get the graphite projects the value they deserve.

  •        Politically stable location (Saskatchewan)
  •        Very high grade vs. peers
  •        One of the only graphite explorer’s on the venture
  •        Fast tracking potential
  •   Spin out will value graphite assets


The Hunt For The Next 10 bagger! 

The company trades with a tiny market cap of about 8.4 million, for a company with 4 world class exploration projects I think this is very low. Expect a gradual rise in share price as the company matures, this is a very new company that was recently formed and with more promotion and awareness things are going to change QUICK! This company over higher than 10 bagger potential! It still only has a market cap of 84 million as if it were ten bags! Not often do you get a chance to get in at the ground floor! Now is your chance to grab it by the horns! If you act now you will get a FREE share of Strike Graphite!

In conclusion to this short blog, I rate Strike Gold a screaming buy, the graphite and gold projects hedge each other out very well in my opinion. Graphite is a play on the industrial strength of the economy while gold is a great hedge to have if the economy goes in the gutter again! You can't lose on this one folks.

For More Information Visit www.strikegoldcorp.com 

Tuesday, 2 August 2011

Unity Is Spinning Outta Control!!!

Unity Energy Corp  UTY.V

SP: $0.35
S/O: 21.26 Million
Market Cap: $7.4 Million
http://unityenergycorp.com/

Initiating coverage @ $0.35
Rated: Strong Buy
Discourse: Ownership of Stock

Has there ever been a more perfect time to invest in uranium? For those that missed the initial uranium rally earlier this year before Fukushima there is a “second chance” Unity Energy is aggressively developing there properties. This 7 million dollar company has the potential to be the next big developer in the Athabasca Basin. 

They are also spinning out a key gold asset in northern Saskatchewan. Never has there been a better time to buy uranium stocks and Unity in particular. In the words of their commander in chief  “Positive results indicated at Dickens Lake justify this gold asset creating its own market and raising funds for further exploration and to add shareholder value. Unity Energy's roots shall remain grounded in energy through exploration of its significant portfolio of prospective uranium properties in the Athabasca Basin." - Anita Algie President and CEO Unity Energy.

Uranium is going to get hotter than Fukushima  


The longer term fundamentals of the sector remain solid and many countries have publically stated their strong continued commitment to nuclear energy.

 
The uranium spot price looks like it is just about to break out again, the current price is $54 a pound, a far cry from this years high of $75.00, so if you missed round one on the uranium breakout this is the “second chance” we all hope for but never seem to get.
 
The power hungry citizens of China and India don’t care where the energy comes from they just want it, China has 25 nuclear reactors under construction and India is the cutting edge leader in developing Thorium based reactors, With oil once again rocketing Uranium stocks have never looked so cheap. 

 
Recently I have started to notice consolidation in the uranium sector, Bannerman Resources (BAN:TSX) recently has had a offer from a Chinese uranium company to buy them out.
 
Investors have realized that modern nuclear technology is safe and reliable, the mishaps that happened in Japan are all due to mismanagement and there poor safety record, At a meeting of the G8's Nuclear Safety and Security Group, held in Tokyo in 2008, an IAEA expert warned that a strong earthquake with a magnitude above 7.0 could pose a "serious problem" for Japan's nuclear power stations, In March 2006 the Japanese government opposed a court order to close a nuclear plant in the west part of the country over doubts about its ability to withstand an earthquake. Japan's Nuclear and Industrial Safety Agency believed it was "safe" and that "all safety analyses were appropriately conducted"
 
I believe that Unity Energy will eventually become a household name such as Hathor or Fission with the same or more potential.

 
Are you in it for the Green or the Gold?
 

Unity has the perfect combination! Uranium and Gold, I believe they both hedge each other out perfectly! Unity recently decided to spin out there Northern Saskatchewan gold project, into a new venture called Patrone Gold. I believe this is a great decision, the company is not getting any value for the gold properties, the recent spin out of Prophecy is a great example of a successful spin out, (NKL:TSX). Everyone knows about the uranium projects, but the golden question is who knows about Unity’s GOLD PROJECT IN LA RONGE GOLD BELT? Unity completed a VTEM survey of the Dickens Lake Project and final results and interpretation are expected in the near term This gold district has produced 600,000 oz in the past, The Dickens Lake Gold Project is getting NO value right now with current valuations,expect the stock to rocket when it starts trading.

Time to pick your favorite lake.
Waterbury Lake? McKenzie Lake? Close Lake? Lampin Lake? Thorburn Lake?  Hoppy Lake?  Kirkpatricks Lake?  Dickens Lake?


At least
if the uranium mining business collapses Unity shareholders could profit from luxury lakeside condos!

The lake that interests me the most is Thorburn, the property is surrounded by Cameco claims and it is very close to Hathor’s Roughrider Zone. Surrounding companies have drilled with tons of success, uranium has been found in percentages as high as 10% over 9 meters in surrounding areas. Preliminary ore reserve calculations indicate that the project contains approximately 5 million pounds of uranium as a area is defined expect this number to rocket. The Thorburn property is 14.5km south east of the world's largest and highest grade uranium mine,Cameco’s Cigar Lake mine.

Surrounding Drillholes of Interest:

  • 4m at 3.5% U
  • 44.50m at 2.0% U
  • 9.90m at 10% U
  • 10.40m at 7.0% U
As you can see these grades are VERY high clearly there is mineralization running through the property. The geology is very similar to the large uranium deposits that are found in the Athabasca basin. 
 
Athabasca Basin 101
So investors unfamiliar to uranium are probably wondering what the hell is the Athabasca Basin? Why should I care about this Basin? Where is it? 
 
The
Athabasca Basin is in northern Saskatchewan, it is 100,000 km squared. The Athabasca Basin accounts for 30% of the world's uranium production. The area currently hosts reserves upwards of 650 million pounds of uranium. 
 
The Athabasca Basin is host to unconformity-associated type Uranium deposits. Mineralization occurs at, above or below the unconformity. This area is largely controlled by AREVA and Cameco, although currently there are 20 or so Juniors drilling and outlining deposits. Unity has key properties in all the right places, they are a area play to Fission and Hathor, they are also conveniently located near Cigar Lake. Cameco as a large scale producer will only buy out the largest deposits, companies like Hathor and Fission need to increase their
deposits sizes and land holdings in order to catch the attention of Cameco and AVERA.

Infrastructure points of outlining a uranium deposit in the Athabasca Basin
  • Ample power supply nearby
  • Easy access to mine site from road
  • The Athabasca Basin is the hub for all uranium core sample testing
  • Abundant water supply
  • A workforce that is highly experienced in developing uranium deposits


Anita’s Running A Tight Ship 

When I first got involved with Unity, the key reason that got me interested was the share structure, this company has a tight float with only 21,142,000 shares outstanding and a market cap of around 7 million dollars this thing can move really hard and when  there are any indications of serious mineralization this stock can easily go up 10x and still have a market cap lower than Fission and Hathor. Another key point I would like to put out is that  49 North (FNR:TSX) owns 2,490,000 shares or almost 12% of the float. 49 North is a Saskatchewan based resource company, when it comes to knowing the right plays in Saskatchewan I would trust them to know what is best in there own back yard.

 
Another point I would like to mention is that Unity has never done any dilutive financings, all financings have been higher than the previous financings or the same, the company recently did a PP that just came free trading which shows in the stock because the recent financing was almost 18% of the float.

Friday, 22 July 2011

Securing Critical Supply

Securing Critical Supply

Formation Metals  FCO.TO

SP: $1.00
S/O: 90.7 million
Market Cap: $90 million
http://www.formationmetals.com


Initiating coverage @ $1.00
Rated: Strong Buy
Discourse: Ownership of stock/warrants


On this edition of Resource Corp, I am going to feature a cobalt company that is feeling blue. Formation Metals has somewhat under preformed the market in the last 52 weeks; but I sense that the market will change its tune very soon!

Idaho's new walk to fame.


Potatoes were Idaho's claim to fame but Formation Metals will put the great potato state back on the map with this sizable cobalt deposit. I know it is hard to believe but high grade cobalt can be found outside of the Congo, so if you want politically de-risked exposure to cobalt Formation is the place to be. 65% of the world's cobalt comes from Africa and if I was a betting man I would say that 45% of the 65% came from Congo, if anyone owns First Quantum they know the pain first hand of investing in Congo, they recently had a mine that got seized, so if a company with a 14 billion dollar market cap gets robbed like that you betcha that the pirate government of Congo would not be shy on stealing your exploration companies project! The Ram project is the only feasible large scale cobalt deposit in North America.

Cobalt 101

So you guys are probably wondering why I am not blogging the hottest gold play with 1600 gold, why Cobalt? What the hell is Cobalt a color?
Cobalt is a gray, hard, lustrous metal, which was first discovered in 1739 , most people think that the metal is blue the color Cobalt is blue but the metal is plain old gray. Cobalt is a rare base metal, most of it is a byproduct of copper or nickel mining. It is very rare to find a pure cobalt deposit like the Ram Project.
About 32% of Cobalt is used for industrial uses such as paints, drill bits, ball bearings, and 36% for environmental such as solar panels, fuel cells, and batteries for hybrid vehicles, and 22% for strategic uses such jet engines and turbine blades and 9% for electronics including propulsion systems, cell phones, memory chips and hard disk drives. As you can see, Cobalt is a critical metal with many uses. With China and India going on a aircraft buying spree Cobalt will be in high demand, trust me the skies are looking blue for cobalt producers. The Paris Air Show shattered aircraft sales records, for those of you not familiar with the Paris air show it is the world's biggest convention for aircraft sales. Boeing estimates India alone will buy $150 billion dollars of jets in the next 20 years.
Securing the safe and consistent supply for rare elements such as Cobalt are key to the security of North America, right now we are the largest consumers of Cobalt and all of it is imported, I believe that Formation will be a key supplier of Cobalt in the USA, if you are a Formation shareholder you are probably sipping pina coladas and laughing because Formation Metals owns the sole cobalt deposit in North America!


MineOnomics

The capex for the Idaho cobalt deposit stand at $141,903,963. The IRR using a conservative $22.52 cost per pound price is 22.30%, currently the spot price of cobalt is at $18.25, the price of Cobalt was over $50 before the great recession of 2008.  Proven and Probable Reserve category of 29.5 million pounds of cobalt, 31.4 million pounds of copper and 37 thousand ounces of gold. The project is expected to have a 10 year mine life, with further drilling this can be expanded as the project is still open in directions. The company has 20 targets and only four have been drilled, only one is used for the Project's proven and probable reserves. This project has the potential to be MASSIVE.  The company plans on producing 3.3 million pounds a year with a 22 dollar average cost the company will bring in almost 75 million dollars after subtracting 25 million for the cash cost you are left with approximately 50 million dollars in earnings a year.

Buy truckloads of Formation NOW!!!

 
Jennings Capital recently put a speculative buy rating on Formation for $2.60, this thing is the real deal. The management team has made spectacular deals, they picked up a Hydro Metallurgical plant about 200 miles away for 1.2 million, the replacement cost for the plant is roughly 80 million! They have also have raised money in the toughest of markets.
The Ram mine has near term production potential, the company is on track for construction. High lead items have already been ordered and the company is about to enter a highly lucrative construction period, usually mining companies appreciate drastically because of constant news flow.
Formation also has 2 "secret" uranium projects in Saskatchewan, they have a JV with Cameco and AREVA, the two heavyweights in the uranium industry. The company also has a copper project in Idaho, I am sure once there is cash flow coming in the management at Formation will want to dip there toes in more projects.

Remember a 80 million dollar PP was done at $1.50 earlier this year, so by buying the warrant and the share you are paying $1.28, you are getting a better deal than the big boys!!!
I would recommend picking up the warrants along with the shares for extra leverage, if what me and the boys at Jennings Capital are thinking is true expect a 10 bagger within a few years, add all the pieces together and I think that Formation Metals is a very strong buy at current prices, I see very little downside and tremendous upside!


Sunday, 17 July 2011

The golden time to buy gold!

Never in my years of investing in commodity stocks have I seen gold stocks trade at such low valuations.
Producers are trading at there lowest price per earnings!  Why? People are doubting this gold rally! Gold is not in a bubble, gold will be in a bubble when gold stocks are trading 30-40x earnings; When everybody and there grandmother is filling there portfolios and pockets with gold shares then I will be the first to say that we are in a bubble, and trust me gold will one day be a bubble. Legitimate deposits are trading at 60-100 dollars a oz. something has to give!
We are going to hit 1700 dollar gold this year mark it on your calender, the catalysts behind it will be Qe3, the gold rally in September, Investors rushing into gold as a safe haven from depreciating currencies, inflation, debt downgrades... The list is ENDLESS.
Now that I have gotten rid of the preface of this article lets get into the goods, here are the stocks that I think will outperform the markets, and unlike other bloggers  that like to PUSH stocks I will give you my 2 cents on why  I think they will outperform. The stocks mentioned below will be split into three asset classes; explorers for the dare devils advanced exploration for the gamblers and producers for the risk adverse!

Explorers: 


1) ROG.V   Rox Gold


Shares Outstanding: 49 Million
Cash: 6.5 Million
Market Cap: 20.85 Million
Most Recent Stock Price: .55  


The main project Rox Gold has is the Yaramoko project in Burkina Faso, they optioned this from riverstone resources. The company has had great success in there drill program highlights include 6 meters of 24.62 GPT, 62 meters of .62 GPT, 12m of 5.6GPT and 20m of 2.20GPT.
The company is planning on another aggressive drill program that will consist of 5000m, the company is cashed up, management seems to be top notch. They are also in a very hot gold district. I expect phase 2 drill results to be in line with phase one drill results. The geology seems like the project is of significant size.

This is a high risk high reward stock, if drill results are inline with phase one drill results expect the stock to rocket, a PP was done at .75 cents recently so you are getting in at a lower price than the big boys.


2) RPM. V   Rye Patch Gold


Shares Outstanding: 142 Million
Cash: 9 Million
Market Cap: 48.2 Million
Most Recent Stock Price: .34

Rye patch has a excellent management team, together the management has found 80 million oz of gold, seems like to me that these guys are magnetically attracted to gold! The company has 3.1 Million oz of gold outlined and 40 million oz of silver. They have a LARGE land position and they are located in mining friendly Nevada. Management puts this company in the best words, they are a supermarket for large mining companies, RPM does not have the desire or plans to become a producing miner, they want to sell or spin out properties. There goal is to become a 10 million oz junior and they are well on the way with a limited drill program they have been having great success.
The key project for RPM is the 100% owned Wilco project but they also have another 3 great projects. Insiders own 8 % of this puppy while Kinross owns 15% and a few us funds own 35% of it.


Advanced Exploration: 


1) NES.V   Newstrike Capital


Shares Outstanding: 111 Million
Cash: 20 Million
Market Cap: 260 Million
Most Recent Stock Price: $2.50

Newstrike Capital is a gold exploration company based out of Vancouver with there main project being in mexico.
There main project the Ana Paula project was bought from Goldcorp in 2010, Goldcorp has done a lot of work with the project, lots of early exploratory drilling. The company has a large portfolio of properties. Luckas Lundin is also a significant shareholder in the company.
The drill results this company has put out this year are the creme of the crop, the best drill holes I have seen all year, highlights include 190M of 3.52 GPT and 116m of 4.71 GPT and 112M of 2.51 GPT
The company already has a project that I think is mineable all the projects in this district are well over 3 million oz, significant players in the region are Goldcorp and Torex gold. This Jr is on its way to being a producer in a few years!

2) GCU.V  Gold Canyon Resources


Shares Outstanding: 96 Million
Cash: ( I could not find the exact number but I am saying ~ 14 Million)
Market Cap: 230 Million
Most Recent Stock Price: $2.43

Gold canyon has a very very interesting management team, the company spends all there dollars on drilling. I have never seen a exploration company spend LESS on promotion; This isn't a bad thing trust me, if all junior miners played the way Gold Canyon did the venture exchange would be a great place to invest. I think they are trying to drill out a 10 million oz deposit and then there ultimate goal is to sell it. They have quite a few other projects that they want to dip there hands in once they have ample cash.
The downside to this is that the company isnt fairly valued at these prices at ALL. The company is trading at around 60 dollars a oz! In Canada!! The worlds safest mining district!
The company recently did a PP, they are fully cashed for the foreseeable future. There main project is the spring pole lake project. highlights include 28.5m @ 19.75g/t au within 100.5m @ 7.23g/t au and 4.5m @ 36.21 g/t au within 111m @ 2.03g/t au,  30m @ 5.69g/t au within 50m @ 2.56g/t au.

These are monster drill results for a monster company, right now I am sure GCU wants to get the grades up and bring the tonnage alot higher. I can see GCU north of 12 dollars within a year if gold keeps up the pace and if the boys at Gold Canyon keep getting lucky!


Producers: 


1) GBG.TO Great Basin Gold


Shares Outstanding: 453 Million
Cash: 68 Million
Market Cap: 1.1 Billion
Most Recent Stock Price: $2.05

Great Basin Gold, the producer that trades at the valuations of a driller. GBG has 453 million shares outstanding, yes it is high but there are also two producing mines backing up this baby. 
Great basin Gold is a mid tier producer that is focused on becoming a large producer. The company is slated to produce 330,000 oz a year in 2012 with a average cash cost of about $500.
The Company has 13.6 Million oz in the measured and indicated category, these guys have gold and TONS of it.

Great Basin also has tons of exploration potential, but I am buying this because a senior will snap this company up soon, its just a matter of when. With Burnstone and Holister in production this will be a cash cow. I know this company isn't as exciting as the latest gold play in the Congo but expect this to be a ten bagger in a few years, that is if they can get the poison pill in place.
Shorters be warned....


2) BGM.V   Bakerville Gold Mines


Shares Outstanding: 87 Million
Cash: 12 Million as of November 2010
Market Cap: 135 Million 
Most Recent Stock Price: $1.70

The little gold company that could! The best way to describe Bakerville, the company is slated to produce 40,000 Oz of gold this year, tiny I know but when you compare it to the market cap of this lil company you realize how undervalued this thing really is. This year they will prodce 62 million dollars worth of gold at a average cost of 1550 a oz.
The company has been very careful about selling the gold in strategic times, and they are also not growing "too fast" thereby avoiding dilution. A resource update on Bonanza ledge is pending. The company has a few good projects in the pipelines, I can seem them producing 250,000 Oz a year in 2013. Lots of growth and the exploration potential is massive, they are permitted to drill 300,000m in one project alone. This is great potential and usually unheard of. 

Well that was alot of writing, I am sure it was a chore to read but now you have the greatest gold companies in your hands, be very careful with what you do with this POWERFUL information. Please rate my blog a 5 on stock house and make sure you guys subscribe! I will be posting great articles and my thoughts on the market on a weekly basis.


Thanks for reading!